Financial technology has transformed how Americans manage their money. From mobile banking apps and digital wallets to cryptocurrency exchanges and commission-free investment platforms, fintech has made financial services faster, more accessible, and increasingly convenient. However, as more wealth moves into digital ecosystems, some consumers are reconsidering the importance of owning tangible assets outside the traditional banking system.
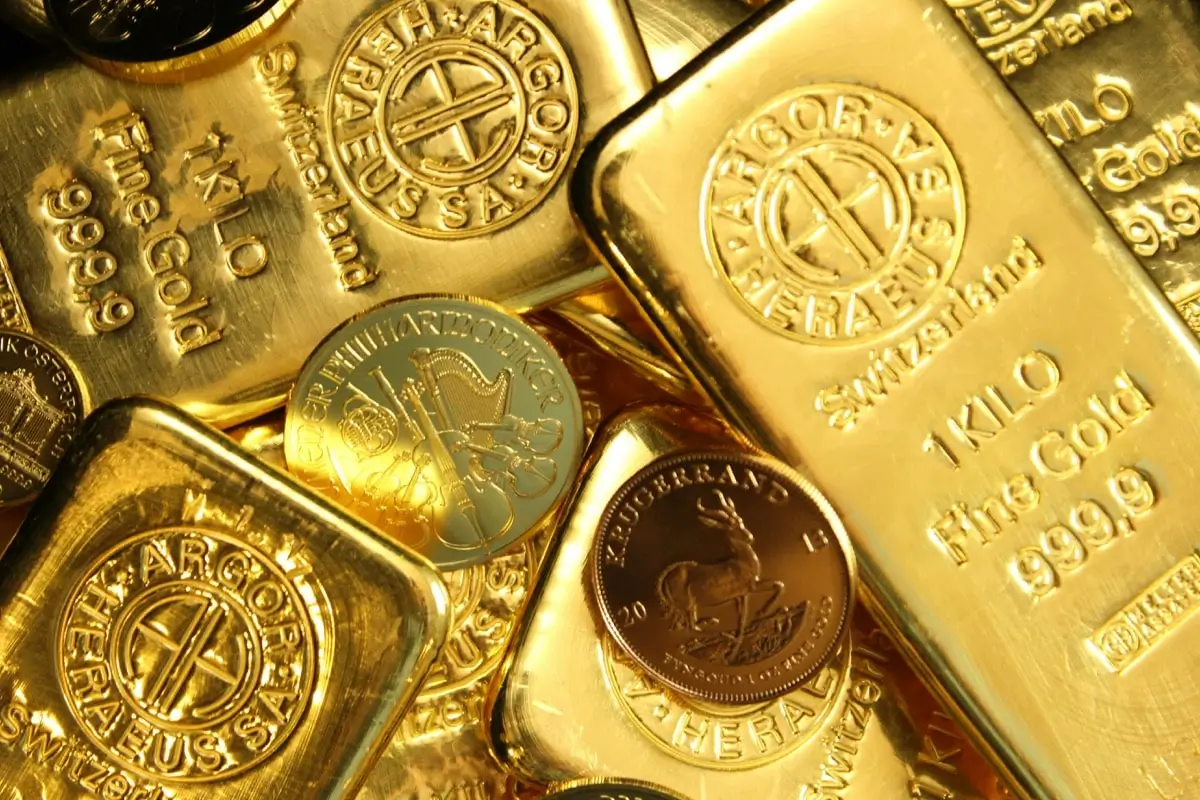
For users of popular fintech platforms such as Chime, Coinbase, Kraken, and other digital financial services, physical gold bullion offers a different approach to wealth preservation. Unlike digital account balances, cryptocurrencies, or brokerage holdings, physical gold coins and bars can be owned directly without depending on a financial institution’s solvency or a technology platform’s continued operation.
As gold prices respond to inflation expectations, geopolitical uncertainty, central bank purchases, and changing monetary policies, fintech users are increasingly considering how precious metals might complement their digital holdings. While gold prices fluctuate and bullion does not guarantee protection against financial losses, physical gold provides a tangible asset with a long history of global recognition and demand.
Physical Gold Reduces Dependence on Digital Financial Institutions
One of the primary reasons fintech users consider physical gold bullion is the ability to hold an asset without relying on a bank, brokerage, or cryptocurrency exchange.
Many neobanking platforms operate through partnerships with traditional banks rather than holding their own banking charters. Although eligible deposits may receive FDIC insurance through partner institutions, the relationship between fintech providers, payment processors, and underlying banks can introduce operational complexities.
The 2023 collapse of Silicon Valley Bank demonstrated how quickly concerns about financial institutions can disrupt access to banking services.
Physical gold bullion held directly by its owner does not represent a deposit or an unsecured claim against a financial institution. Its ownership is independent of the financial condition of a banking app or cryptocurrency exchange.
However, physical ownership introduces other responsibilities, including secure storage, insurance considerations, and protection against theft.
Protection Against Cyberattacks, Account Freezes, and Platform Failures
Digital financial services depend on interconnected technology systems, including cloud infrastructure, cybersecurity networks, payment processors, and third-party banking partners.
When these systems experience outages, consumers may temporarily lose access to their accounts or encounter delays transferring funds.
Automated fraud detection systems can also trigger account restrictions or additional verification requirements, sometimes preventing customers from immediately accessing their money.
Cryptocurrency exchanges face additional cybersecurity risks, including phishing attacks, compromised credentials, and digital asset theft.
Physical gold offers a different security model.
Gold coins and bars stored in a secure home safe or professionally managed private vault cannot be stolen remotely through a compromised password or cryptocurrency wallet.
For fintech users concerned about concentrating their wealth entirely within digital platforms, directly owned bullion provides an alternative that does not require continuous access to online financial infrastructure.
Physical Gold Remains Accessible During Internet and Power Outages
Modern banking relies heavily on electricity, telecommunications, and functioning payment networks.
Severe storms, natural disasters, cyberattacks, and major infrastructure failures can temporarily disrupt ATMs, electronic transfers, and mobile banking applications.
Physical gold does not require internet connectivity, electricity, or authentication through a mobile application to remain in its owner’s possession.
This distinction can appeal to consumers who value financial preparedness and the ability to maintain direct control over part of their wealth.
However, gold is not a substitute for emergency cash. Selling bullion generally requires finding a willing buyer, verifying authenticity, and agreeing on a transaction price.
For everyday emergencies, readily accessible cash remains important, while physical gold may serve a longer-term wealth preservation purpose.
Diversifying Beyond Cryptocurrency and Technology Stocks
Fintech users frequently participate in digital investment markets, including cryptocurrencies, technology stocks, exchange-traded funds, and other financial products.
Although these assets offer different opportunities, they can experience substantial volatility during periods of financial uncertainty.
Cryptocurrencies and growth-oriented equities may also decline simultaneously when investors reduce exposure to riskier assets.
Physical gold has historically demonstrated different performance characteristics from many technology-related investments.
Gold does not generate dividends or interest, but its value is influenced by factors including currency movements, inflation expectations, interest rates, and global investment demand.
Adding physical gold bullion can therefore provide exposure to an asset whose underlying drivers differ from those of cryptocurrencies and technology stocks.
Diversification does not eliminate risk, and gold can experience significant price declines alongside other financial markets.
Gold Bullion as a Long-Term Inflation and Currency Hedge
Another reason fintech users explore physical gold is concern about the long-term purchasing power of fiat currencies.
Money held in digital checking accounts or low-yield wallets may lose purchasing power when inflation exceeds the interest earned on those balances.
Gold has maintained a recognized monetary and investment role across centuries, long before digital banking or cryptocurrencies existed.
Unlike fiat currencies, gold cannot be created through central bank monetary policy. Its supply depends on mining production, recycling, and existing above-ground inventories.
This relative scarcity contributes to gold’s appeal among individuals concerned about government debt, monetary expansion, and currency depreciation.
Nevertheless, gold does not consistently outperform inflation over shorter periods, and its purchasing power can fluctuate substantially.
Global Recognition and the Benefits of Direct Ownership
Physical gold bullion is recognized internationally, with established markets for widely traded gold coins and bars.
Products such as American Gold Eagles, Canadian Gold Maple Leafs, and recognized refinery-produced gold bars are familiar to precious metals dealers around the world.
This recognition can make physical gold easier to value and resell compared with less widely recognized collectibles.
Fintech users interested in direct ownership may also appreciate that physical bullion can be held outside brokerage accounts, cryptocurrency exchanges, and digital payment platforms.
However, resale prices, dealer premiums, identification requirements, taxes, and local regulations vary by market.
Why Physical Gold and Fintech Can Complement Each Other
The growing appeal of physical gold does not necessarily represent a rejection of financial technology.
Digital banking platforms offer convenience, speed, and accessibility, while physical bullion provides tangible ownership and reduced dependence on digital intermediaries.
For consumers seeking a more diversified approach to managing wealth, these characteristics can complement one another.
Whether purchasing gold coins or gold bars, understanding spot prices, dealer premiums, storage requirements, and resale considerations remains essential.
Ultimately, physical gold bullion offers fintech users something digital platforms cannot fully replicate: direct ownership of a tangible asset that exists independently of an internet connection, banking application, or cryptocurrency exchange.
Disclosure: This article is provided for educational and informational purposes only. Gold prices fluctuate, and physical gold involves market, storage, security, and liquidity risks.