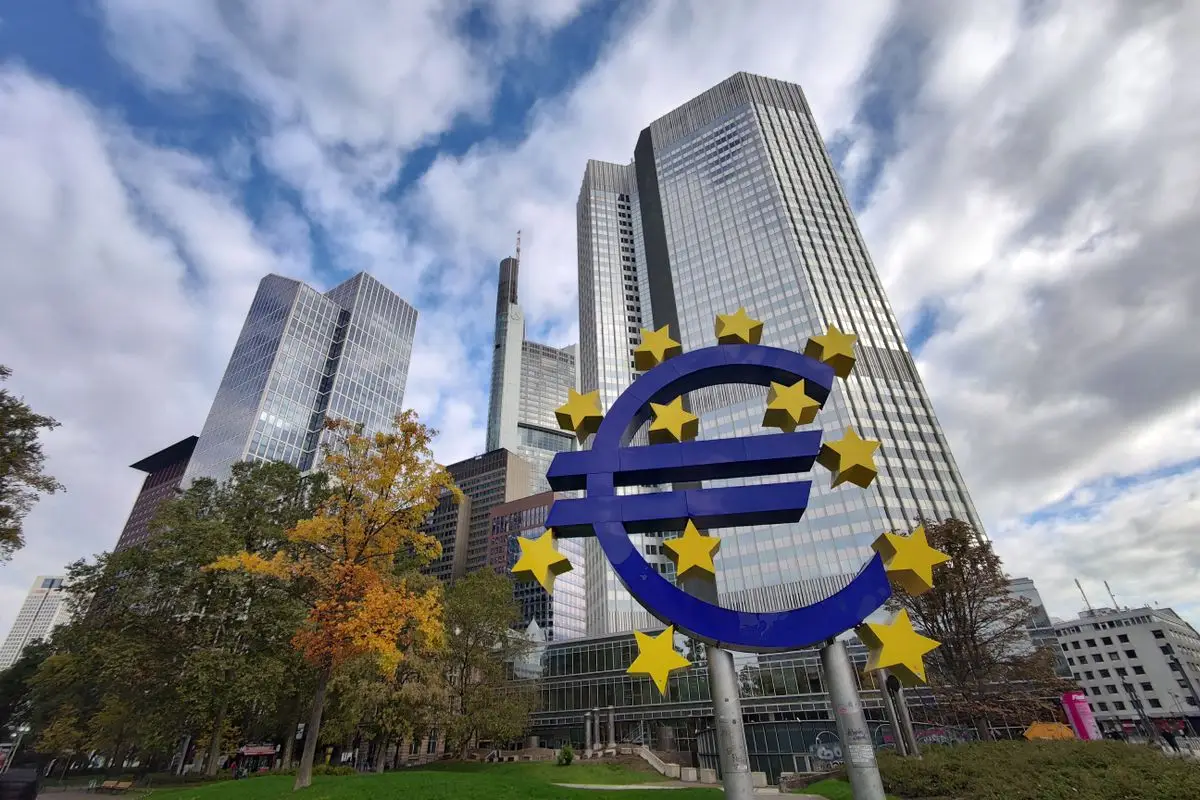
The European Central Bank has selected two groups of network service providers to connect payment service providers and national central banks to the digital euro service platform.
The contracts support preparation for pilot testing and a possible future issuance, but they do not decide whether the digital euro will be launched.
The first group consists of Deutsche Telekom and Nexi Payments. The second brings together Telefónica de España, Telefónica Global Solutions and Indra Soluciones Tecnologías de la Información.
Their role is to provide the connectivity layer between participating institutions and the components of the digital euro platform. Payment service providers that eventually offer the digital euro will be able to connect through either provider.
The 10-year agreement with Deutsche Telekom and Nexi has already started. It will initially cover the connectivity needs of the digital euro pilot project, which is expected to begin next year. The contract with the Spanish providers is scheduled to start in May 2027.
Both groups are expected to be ready by 2029 to deliver the connectivity services required for a potential issuance, should the ECB decide to proceed. These dates concern service preparation and should not be read as a fixed launch date for the digital euro itself.
Nexi and Deutsche Telekom said they will offer a robust and scalable connectivity and mediation platform designed to enable the end-to-end exchange of digital euro transactions across the ecosystem. The architecture is intended to support high levels of scalability and elasticity so that resources can be adjusted according to transaction volumes and peak usage.
Gottfried Ludewig, who leads the public sector and health business at Deutsche Telekom, said the company is involved in building the kind of secure infrastructure Europe needs if it wants to reduce dependence on outside providers. It also would like to keep more control over its systems.
The ECB’s own pilot description, updated in an FAQ on October 28, frames the exercise as a limited test of a beta version. Participating institutions, staff and merchants will try the system in practice to see how it behaves technically, operationally and for users.
According to the FAQ, the operational part could start in the second half of 2027 and run for a year. The document is careful to note that none of this work decides whether the digital euro will actually be issued. The decision will ultimately depend on legislation.
Even a minor test may reveal problems that do not become obvious in a laboratory environment. Payments may not go through, onboarding may not go as fast as planned, merchants may come across reconciliation challenges and certain scenarios may take longer than anticipated to be resolved. These results are informative irrespective of whether a high number of people and transactions are involved.
What is visible for users is the payment interface. What banks and payment providers require are trustworthy means of sending instructions, confirmations and operational data. The approach used by a certain participant may work in a single case but will not be effective if multiple institutions have to send messages simultaneously.
Using two different providers provides some options. However, it does not imply that the system can operate flawlessly in all cases. The modern reality is what happens if the connection is lost, whether a message can be resent without triggering a duplicate payment and what mechanisms the system employs to determine whether a payment was made or not.
Selecting the providers shows that the ECB is moving past the concept stage and into concrete preparation. It does not mean a public digital euro is already approved or available. Stablecoins, conventional bank deposits and CBDCs are all digital forms of money but operate on different principles and involve different responsibilities. A connectivity agreement does not change these principles or determine what instrument people will use in what instance.
The only aspect that truly matters is the payment details: who takes responsibility for the customer, who can take part in the payment and how money moves between participants. It remains to be seen whether the system works, whether the trial runs smoothly and how people proceed with launching the payment system more widely.